 How-to
Impact of Granny Flat on Resale: What Buyers Pay For
Table of Contents
- How a Granny Flat Actually Changes Your Property's Resale Value
- Granny Flat Property Valuation: What Valuers Look For
- Selling a Property With a Granny Flat: Buyer Pool and Demand
- Granny Flat Building Approval and Resale: Why Compliance Decides Your Price
- Granny Flat Rental Income and Capital Gains Tax: What You Keep After the Sale
- Net Resale Return: Income Earned Plus Value Uplift, Minus Costs
- A Pre-Sale Checklist for Owners With a Granny Flat
- Conclusion: Making the Granny Flat Work for You at Sale Time
- Frequently Asked Questions
Last Updated: October 13, 2026
How a Granny Flat Actually Changes Your Property's Resale Value
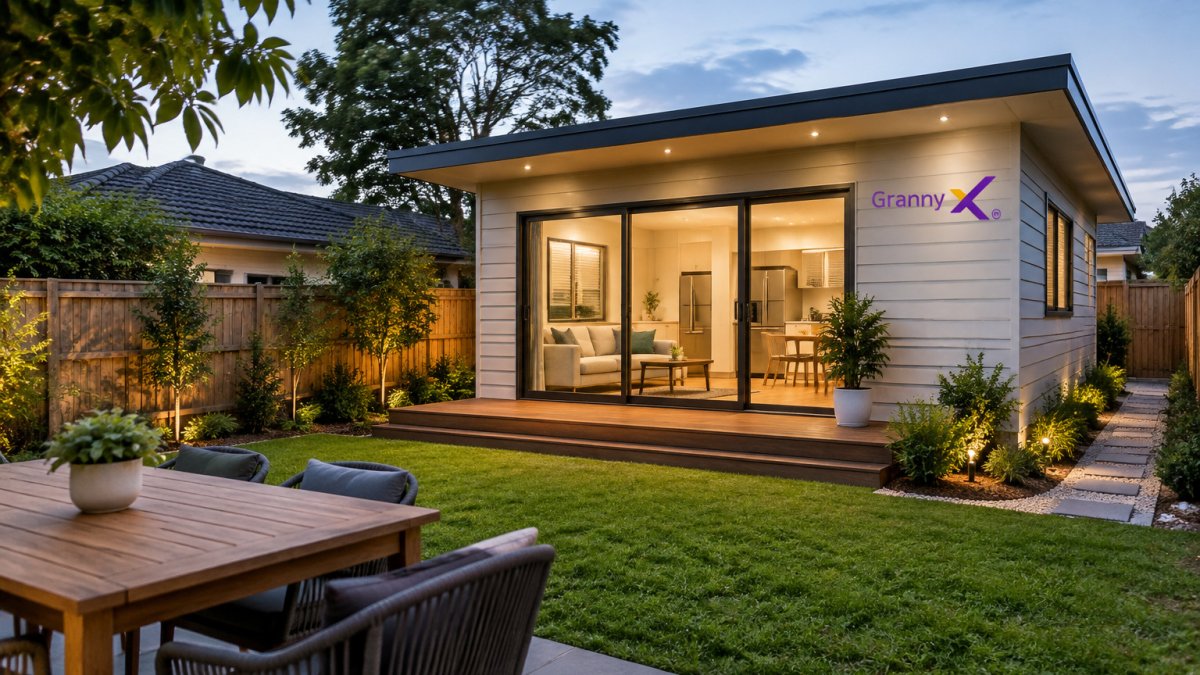
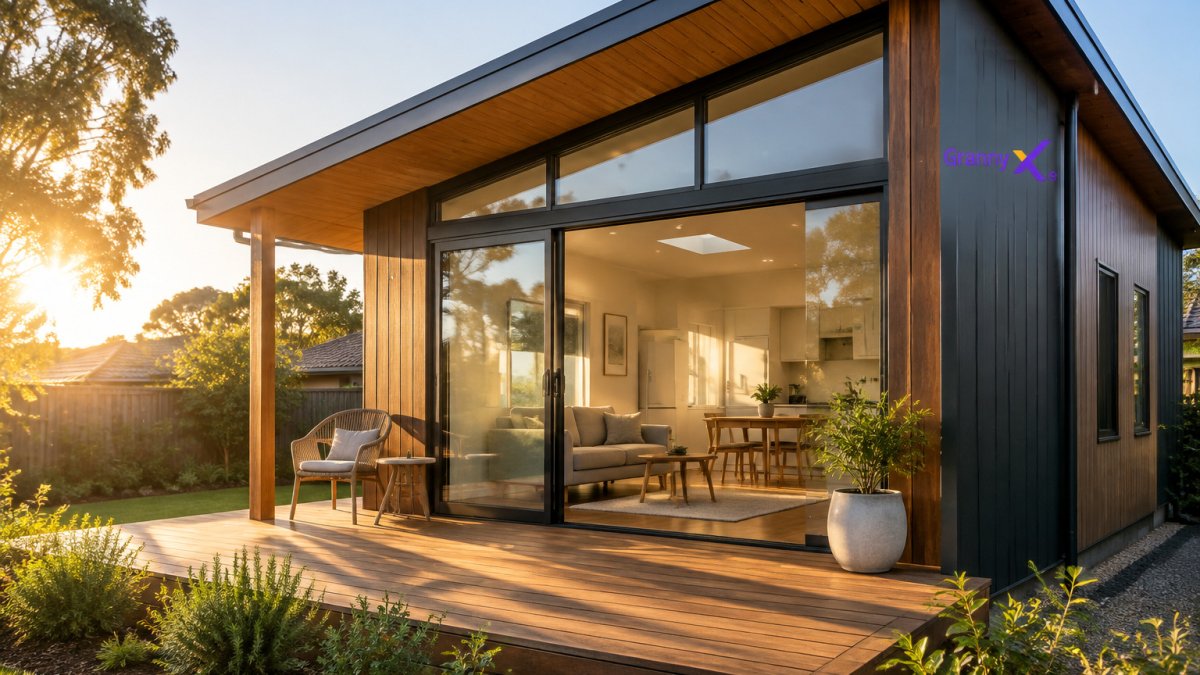
The impact of granny flat on resale is not a simple uplift story. A secondary dwelling changes who wants your property, how a valuer prices it, and what a buyer will pay. Get it right and you widen your buyer pool. Get it wrong and you can narrow it.
At Granny X, we work with owners across Victoria on exactly this question. The honest answer: a compliant, well-built granny flat usually adds value, but the size of that uplift depends on your location, your buyer pool, and whether the dwelling is approved.
Three things drive the outcome:
- Compliance, an approved dwelling is financeable and insurable; an unapproved one often is not
- Income, a rented secondary dwelling shows a buyer real, provable return
- Presentation, design and condition decide whether buyers see an asset or a problem
Below, we break down how valuers assess secondary dwellings, which buyers pay more, and how to protect your sale price.
Granny Flat Property Valuation: What Valuers Look For
A valuer does not add a flat dollar figure for a granny flat. They assess the property as a whole and weigh the secondary dwelling's income and compliance status. The main factors are whether the dwelling is approved and legally lettable, whether it has a separate entrance, kitchen and bathroom, the rent it can realistically achieve, and how it compares to similar properties that have sold.
The Comparables Problem for Secondary Dwellings
Valuers rely on comparable sales. Fewer properties with secondary dwellings sell in any given suburb, so direct comparisons are harder to find. That means the valuer often leans on rental evidence instead. A documented lease helps more than a brochure. If you can show a signed tenancy agreement, rent receipts and a rental appraisal from a local agent, you give the valuer something concrete to work with. Without that, the dwelling may be treated as a minor improvement rather than an income-producing asset.
How Valuers Treat Unapproved Dwellings
An unapproved dwelling is usually valued as a shed or outbuilding, not as a home. It cannot be rented legally, may not be insured, and often cannot be financed by a buyer's lender. In practice, this means the value sits close to zero, and some buyers walk away entirely.
Lenders take a similar view. If the dwelling is not on the title or does not have the required approvals, most lenders will not include its rental income in servicing calculations, and some will not accept the property as security at all.
A common pattern is that an unapproved flat adds nothing to the sale price and may reduce the pool of buyers to those willing to take on the risk.
What This Means for Your Sale Price
The gap between an approved and unapproved granny flat can be the difference between a premium and a problem. Approved dwellings give buyers confidence, financeability and a provable income stream. Unapproved ones shift risk to the buyer, and most buyers will price that risk in. Before you list, confirm the approval status, gather any documentation, and speak to your agent about how to present the dwelling honestly. If it is unapproved, a realistic price guide and full disclosure will save you time and legal risk.
Selling a Property With a Granny Flat: Buyer Pool and Demand
Selling a property with a granny flat changes who turns up to your open home. You are no longer just selling a house. You are selling a house plus an income stream, or a house plus room for family.
Which Buyers Pay More for a Granny Flat
Certain buyers will pay a premium:
- Investors chasing rental yield and dual income
- Multigenerational families wanting independent living for parents or adult children
- Retirees who want family accommodation nearby without sharing a kitchen
For these groups, the granny flat is the reason they are looking at your property at all.
When a Granny Flat Can Slow a Sale
The same dwelling can shrink your buyer pool. Some buyers see maintenance, shared driveways, or a structure they did not ask for. If the flat is poorly built or non-compliant, it becomes a negotiation lever against you. A common mistake is assuming every buyer wants a second dwelling. Many do not.
Granny Flat Building Approval and Resale: Why Compliance Decides Your Price
Compliance is the single biggest factor in the impact of granny flat on resale. An approved secondary dwelling is a legal, lettable asset. An unapproved one is a liability the buyer inherits.
Approval generally means the dwelling meets the relevant planning and building rules for your site. Victoria's planning framework sets out when a small second dwelling can proceed without a planning permit, but building approval is still required. You can check the current rules through Planning Victoria's secondary dwelling guidance.
What compliance gives a buyer:
Book Your Free Site Assessment →
- Confidence their lender will finance the purchase
- Insurance cover for the dwelling
- A rentable, income-producing asset
- No rectification costs after settlement
Granny Flat Rental Income and Capital Gains Tax: What You Keep After the Sale
Rental income and tax treatment shape your net result, not just your asking price. This is where many owners get caught out.
If you rent the granny flat, that income is taxable. It also affects how the main residence exemption applies when you sell. The exemption lets you avoid capital gains tax on your home, but renting part of the property can reduce or remove it for that portion.
CGT Main Residence Exemption and the Granny Flat
The main residence exemption generally applies to your home, but a rented secondary dwelling can change how much of your property qualifies. The treatment depends on your circumstances, including how the property is used and for how long.
Because the rules are specific, confirm your position with a registered tax agent before you rely on the exemption. The Australian Taxation Office guidance on the main residence exemption sets out how it works. Getting this wrong can turn a profitable sale into an unexpected tax bill.
Net Resale Return: Income Earned Plus Value Uplift, Minus Costs
Your real return is not the sale price. It is what you earned while you owned the property, plus the value the granny flat added, minus what you spent. Most owners focus on the uplift and forget the costs that eat into it.
Suppose you build a compliant, one-bedroom granny flat for a total cost of $120,000, including design, permits and construction. You rent it for $350 per week.
Item | What It Includes | Effect on Return |
|---|---|---|
Rental income | Rent collected over the ownership period | Adds to return |
Value uplift | Extra a buyer pays for the dwelling | Adds to return |
Build and approval costs | Design, permits, construction | Reduces return |
Holding and tax costs | Rates, insurance, tax on rent | Reduces return |
Rectification costs | Fixing non-compliant work | Reduces return sharply |
Selling costs | Agent fees, conveyancing, marketing | Reduces return |
A compliant, tenanted granny flat stacks income on top of value. An unapproved one stacks costs on top of a lower price. The longer you hold, the more rent you collect, but the more maintenance and depreciation you need to account for.
Tax and the Main Residence Exemption
If you rent the granny flat, that income is taxable. It also affects how the main residence exemption applies when you sell. The exemption lets you avoid capital gains tax on your home, but renting part of the property can reduce or remove it for that portion. The treatment depends on your circumstances, including how the property is used and for how long. Because the rules are specific, confirm your position with a registered tax agent before you rely on the exemption. The Australian Taxation Office guidance on the main residence exemption sets out how it works. Getting this wrong can turn a profitable sale into an unexpected tax bill.
What to Do Before You Sell
Before you list, gather your build costs, rental records, and any tax advice you have received. A simple spreadsheet showing income, costs and the expected uplift will help you and your agent set a realistic price guide. If the numbers do not stack up, consider whether holding longer, improving the dwelling, or seeking retrospective approval would change the outcome. The owners who get the best result treat the granny flat as a financial asset with a clear profit and loss, not just a backyard extra.
A Pre-Sale Checklist for Owners With a Granny Flat
Work through this before your property goes to market:
- Confirm the dwelling has current building approval
- Gather all certificates, surveys, and permits
- Have a current lease or rental appraisal ready
- Check insurance covers the secondary dwelling
- Ask your tax agent about CGT before you sell
- Fix any maintenance or compliance issues first
- Brief your agent on the income and buyer types
- Decide whether to sell tenanted or vacant
Conclusion: Making the Granny Flat Work for You at Sale Time
A granny flat can widen your buyer pool, add income, and lift your sale price, but only when it is compliant, well built, and presented as an asset. The owners who struggle are usually the ones who skipped approval or cannot show the numbers.
That is where we come in. Granny X handles the whole process, from design and permits through to construction and tenanting. Our builds use concrete slabs, timber frames, and 7-star NatHERS ratings, and we often work within small second-dwelling rules that need no planning permit. You get direct access to your builder and project lead, and a free site assessment to confirm what your land can do.
Book your free site assessment with Granny X and find out what your backyard could earn.
Frequently Asked Questions
Does a granny flat increase a property's resale value?
It can, but the uplift depends on your location, the buyer pool, and whether the dwelling is approved. A compliant secondary dwelling adds usable floor area and rental income potential, which appeals to investors and multigenerational families. Unapproved structures are usually valued as sheds or outbuildings, so the value uplift is far smaller. The rental income itself can also support a higher sale price because buyers factor in the yield.
How does a granny flat affect a property valuation?
Valuers assess the granny flat as a secondary dwelling, not a separate property. They compare it to similar homes with secondary dwellings, check the building approval and compliance, and review the rental income it can generate. If the dwelling is unapproved or non-compliant, the valuer may give it little or no value.
What are the capital gains tax implications of selling a property with a granny flat?
If you rent out the granny flat, that portion of your property may be subject to capital gains tax when you sell, because it is not covered by the main residence exemption. The ATO treats the rental area as a separate income-producing asset. Keeping records of construction costs, rental income, and expenses helps your accountant calculate the CGT liability accurately. Seek tax advice before you sell.
Can a granny flat make a property harder to sell?
Yes, in some cases. If the granny flat is unapproved, poorly built, or limits backyard space that families want, it can shrink your buyer pool. Some buyers also see a secondary dwelling as extra maintenance or a tenancy they do not want. Marketing it clearly as a dual-income or multigenerational asset helps attract the right buyers and reduces the chance of a slow sale.